Register S CorpAfter both filings are done
Equity, payroll setup, the monthly close, and the return start when the IRS acceptance is in the file.
Ask about payday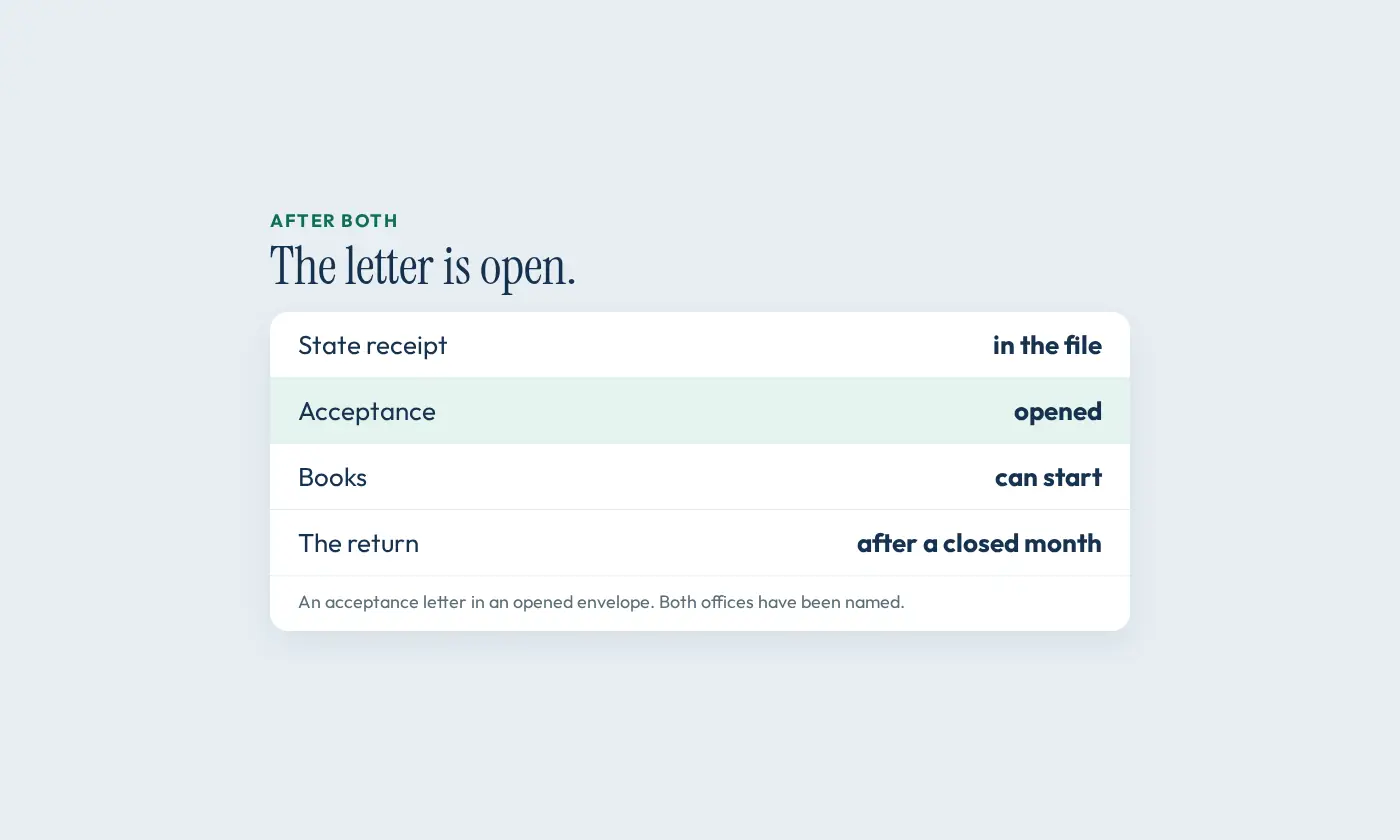
Equity, payroll setup, the monthly close, and the return start when the IRS acceptance is in the file.
Ask about paydayOnce the state filing and the IRS acceptance are both in the file, the equity accounts can show the real amounts. Money the owner puts in is a contribution. Money the owner takes out after wages is a distribution. Profit left in the company stays in retained earnings. Those three amounts need three accounts. One owner-draw account that mixes all three will put numbers on the return that do not match the bank.
New files often arrive with opening balance equity still holding a placeholder. That placeholder is the difference the software could not classify on day one. We clear it by entering the real balances. We do not leave it as a permanent line and then explain it every month. If it is still there after the first close, you will not be able to explain it to a lender.
The accumulated adjustments account is a tax computation. It tracks items the federal rules care about. You do not reconcile it the way you reconcile cash or accounts payable. Do not put that tax account on the balance sheet just because the software offered it. That line does not show where the cash went.
Setup is a list with an order. Federal identification number. State withholding account. State unemployment account. A provider the owner already runs. A written description of the work the owner does, so the wage has a written basis in the work. Deposits and wage forms stay on the provider. The quarterly payroll return, the annual payroll return, and the year-end wage statement are that provider's payday work.
We do not run payday. We do not take over a workforce. We point the provider at the status the acceptance describes, and we check that the wage matches the work before any distribution is paid. If the acceptance is not in the file yet, this list waits. If the provider is set up for a status the IRS has not accepted, those deposits are hard to undo.
Shareholder employees are the usual sensitive case. They work in the company and they own it. The wage is for the work. The distribution is for the ownership, and it comes after the wage once the election is real. A public page will not name a dollar figure for that split. The wage follows the work you do, and that work differs by company.
A month closes when the accounts match the statements and the open items are small enough to list. We catch up the open months before we start a regular monthly close. Unfinished months are completed in this practice, or the work is turned down. If the return is built on a month that never closed, every unmatched difference lands on the return. That costs time. We do not claim a tax savings figure for registering an S corp.
The return follows the closed year and the status the papers support. If the papers support the election, the return is prepared on that basis. If a state does not conform to the federal election, the state return may differ, and we prepare for the state where you file rather than for a generic state. We follow the state where you actually file. That filing office is the one that counts.
Statements and a short report of what changed are part of the month. They are management reports. They are not a signed assurance. If a lender asks for an audit, a review, or a compilation, that request is outside the monthly close described here. Send that work to a firm that signs those reports. The disclosures page explains that limit. This page is the ordinary close.
The acceptance, the provider's name, and a sentence about the work the owner does are the three facts that let this page become an engagement conversation. Bank access comes later, under a written agreement. A first note does not need every login. It needs the tax status and a short description of the work.
If opening balance equity is still on the balance sheet, say so. If wages were never run because everyone was waiting on the letter, say so. Both facts are ordinary. They tell us where the books actually stand.
Steven Palmieri, Tax CFO, keeps this part of the work with the practice. The state office has finished its part. The federal acceptance has finished its part. The rest is the ledger, the provider you run, and the return.
Say whether the acceptance is in the file and whether a provider already runs payday.

You will be talking to the Steven Palmieri practice.