Register S CorpFor Texas owners
The verb on this address still hides two filings, and a Dallas video call is where we set the state receipt next to a federal form that may still be blank on a Wednesday.
Bring the Texas papers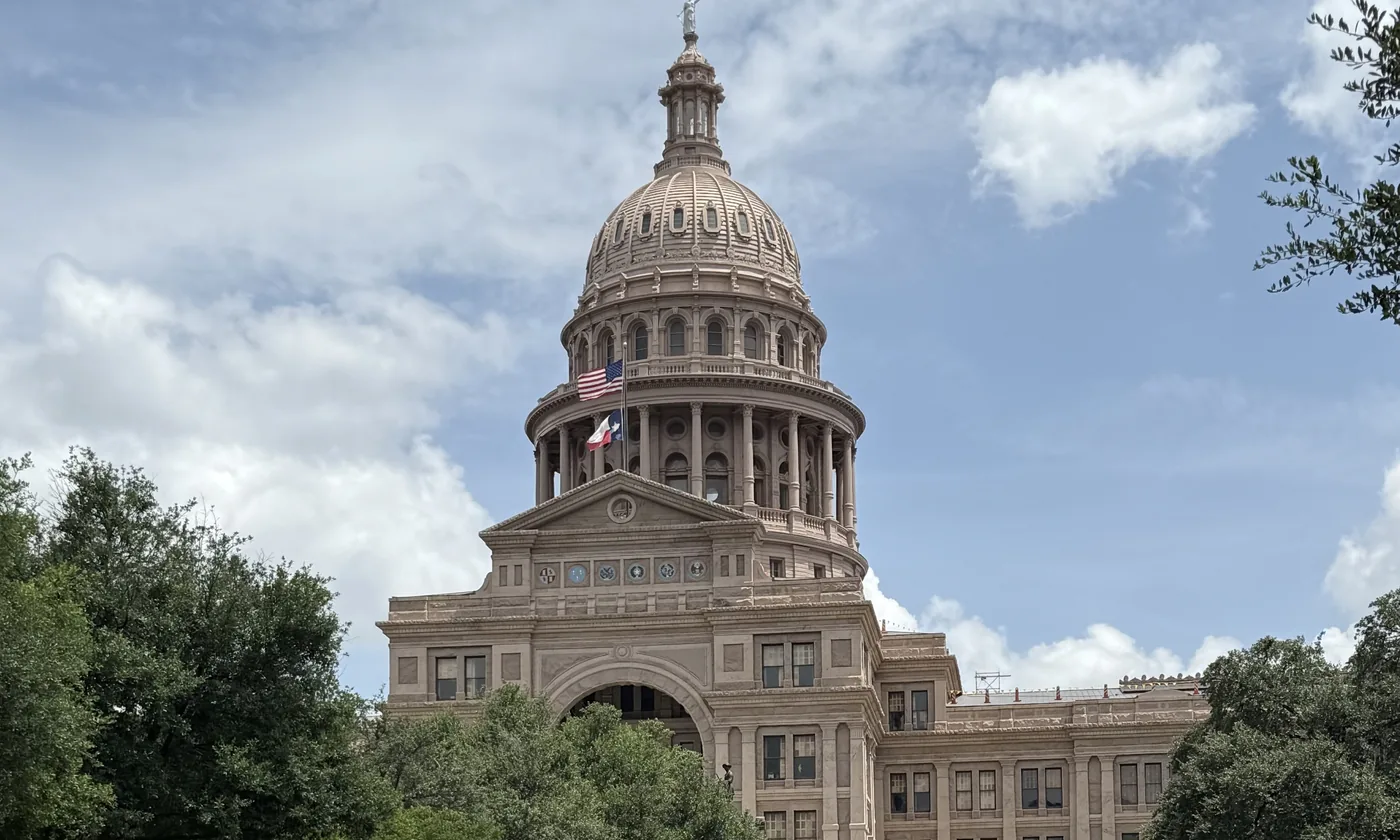
The verb on this address still hides two filings, and a Dallas video call is where we set the state receipt next to a federal form that may still be blank on a Wednesday.
Bring the Texas papersThe practice is in Dallas. An owner whose company sits in Texas, and whose own town is outside Dallas and Fort Worth, meets us on a video call rather than in a room we do not keep. The books travel as files. The monthly close is dated the same way it would be if we were sitting together. Once the video starts, we are all Texans, including the owner who has never driven into Dallas. We will not invent a storefront on your block, and we will not talk as if we had walked it.
Registering a Texas company does not collapse the verb on this address. The Secretary of State still takes the certificate that says the company exists. Form 2553 is still the federal election, and the year still waits on the acceptance letter. The registered agent remains a third job whose only work is receiving mail. Three invoices in a single week are three jobs. A Tuesday state receipt beside a Wednesday federal form that is still blank is the same gap a company in any other state would show us.
Farragutful took the photograph of the Texas State Capitol in Austin that opens this page, and the file is on Wikimedia Commons under CC BY-SA 4.0. The landmark stays on this page because this page is the Texas chapter. The other addresses on the site show federal form pages.
The Secretary of State instructions for a limited liability company certificate of formation name a filing fee of 300 dollars, and that figure should be checked on the instructions the day you pay, because a public page should not freeze a schedule the office can revise. One organizer is enough for that certificate. The organizer may be a person who is 18 or older, or the organizer may be another entity, and Texas residency is not required of the organizer. The organizer signs. Those instructions do not call for a notarization.
The agent job has to be accepted before the certificate is filed. Acceptable agents are people who reside in Texas and entities the state already carries on its agent register. The company is barred from naming itself as agent. Keep the signed agent consent in the company file. The certificate is filed without that consent attached. A mailbox alone fails the test in those instructions, because papers have to be something a person can hand over during an ordinary business day. Beginning in 2022 the certificate also carries an initial mailing address, and that is the address Comptroller tax mail uses. Nothing here copies the destination the Comptroller uses for tax mail.
After the certificate is accepted, the state's record still needs a current agent and a current office. A change in either one is reported to the Secretary of State. Letting the agent or the office go stale is one path toward involuntary termination. The certificate and Form 2553 are different papers. State acceptance of the certificate can leave the federal classification untouched overnight, still disregarded or still a partnership. A nickname stored in bookkeeping software reaches neither the state office nor the federal office.
The Secretary of State instructions are the page we open when the fee, the organizer, or the agent is the question. This paragraph is our reading of that page. The certificate in your folder is the copy that governs.
Form 2553 uses the clock printed in its own instructions, and a company formed in Texas uses that federal clock with no local substitute. The form may go in during the year before the tax year begins, or no later than two months and 15 days after the tax year begins. The state receipt neither starts a second clock nor pauses this one. When those days have already passed, Revenue Procedure 2013-30 is a door someone can try. Naming the procedure is as far as this page goes. An approval handed out in advance is not a promise we make.
Every owner signs Form 2553. One missing signature leaves the form unfinished even when the other boxes look complete. The year moves when the acceptance letter arrives in the folder. Until that letter is there, a wage for an owner who works in the company should wait. On the call we can name which accounts in the payroll service you already use should receive the wage. Payday stays on that provider. We do not run payday, and we do not aim a provider at a status the acceptance has not confirmed.
Once the letter exists, reasonable compensation is written from the work the owner actually did. Anything left after that wage can move as a distribution only when basis and the closed books both allow the move. A public page will not invent how those two amounts split. On the call we ask what the owner did through the year. The provider you already run turns that answer into the wage.
The Comptroller describes the franchise tax as the price of the privilege of doing business as a company formed in Texas or doing business in Texas. Publication 98-806 is the list we open, and we read it as company shapes. A corporation is on the list. A limited liability company is on the list, and that includes a company with one owner and a series company. Banks, S corporations, partnerships, trusts, professional associations, joint ventures, and the other legal entities the publication names are on the list as well.
That publication also names who can skip the tax. Invoicing in your own name, with no company ever formed, generally means this franchise report never begins. When every partner in a general partnership is a human being, this franchise report is usually absent. A limited liability partnership still files, which is the exception inside the partnership row. Chapter 171 exemptions, certain unincorporated passive entities, and the further categories Publication 98-806 names stay off this report. A limited liability company with a single owner stays on the filing list even when the federal return is only that owner's return.
Rule 3.586 holds examples of what counts as doing business in Texas, and Publication 98-806 points a reader there when the examples are needed. An accepted S election does not take the May report off the calendar. Staying with the default federal classification does not take the May report off the calendar either. This franchise report shows up in the year because a company was formed here, separate from whether any federal letter has arrived. The acceptance letter and the Comptroller report can sit in one folder and still answer two different offices.
Total revenue on the franchise report begins with the federal revenue amounts and then subtracts the exclusions in Tax Code section 171.1011. Nobody drafts the May report from a bank download full of unnamed deposits, so a month has to be closed first. The close we need before a federal return is the same close we need before this report.
The base is margin, unless the company qualifies for the shorter EZ computation and actually chooses it. Publication 98-806 lays out four computations. The first computation keeps 70 percent of total revenue. Another computation takes total revenue and removes the cost of goods sold. One subtracts compensation from total revenue. The fourth computation, open since 1 January 2014, removes 1 million dollars from total revenue. A combined group applies one margin method across the group. Once a margin method is chosen, Texas gross receipts sit on top of the fraction and receipts from all states sit under them.
Only money spent to acquire or produce real property or tangible personal property, and later sold in the ordinary course, belongs in the goods subtraction. A company whose work is only services often has nothing allowable in that subtraction. Before we tell a service company that the goods subtraction is closed, we open the industry exceptions collected in section 171.1012. Supplies that are still on a shelf, and have not been sold, stay out of the subtraction.
Compensation on this report adds wages and certain cash together. Wages that already appear on a Form W-2 make up the opening amount. Cash paid to officers, directors, owners, partners, and employees can be added next. Benefits the company already deducts, including workers compensation, health coverage, and retirement plans, may be added in the same subtraction, and a natural person's net share of profits may be added too, still under that person's own ceiling. Labor that shows up on a 1099 stays out. The employer's own payroll tax payments are left out of this subtraction.
The per-person cap for report years 2026 and 2027 is 480,000 dollars. For the two older reports, 2024 and 2025, each person tops out at 450,000 dollars. A 2026 sentence uses the 2026 cap. A 2024 sentence uses the 2024 cap. A wage that already ran through a provider you use can enter this subtraction, up to the cap that belongs to that report year. A draw that never passed through a provider does not turn into a wage just because May is near.
With the acceptance in the folder, pay the working owner through the provider you already run, and treat any remainder as a distribution only when both basis and the books allow it. The K-1 and the W-2 should then match what the bank already showed. The May report is allowed to see both numbers. A distribution does not stand where the wage should have been.
For report years 2026 and 2027, yearly revenue at or under 2,650,000 dollars means the company owes no franchise tax and files no franchise tax report. The information report can still be due, and a later section on this page names who can skip both. Retailers and wholesalers who sit over that revenue line apply 0.375 percent on each of the 2026 and 2027 reports. A company in any other line uses 0.75 percent for those same two report years. The EZ computation is optional. EZ stays available at total revenue of 20 million dollars or less, and the rate on EZ is 0.331 percent.
For report years 2024 and 2025 the threshold with no tax is 2,470,000 dollars. The compensation cap on that older pair of years is the 450,000 dollars already stated. The rates and the EZ ceiling match the later pair of years. Starting with the 2024 report year, a company at or under that year's threshold does not send a separate report that only says no tax was due. The paper that remains is the short report. Form 05-102 belongs to the group of five. Form 05-167 belongs to a company outside that group.
Choosing EZ while revenue is 20 million dollars or under means giving up the items listed on the filing-requirements page, and margin deductions sit on that list. We open the rest of that list with you instead of cutting it down here. The long form is what a company uses when revenue is over the line and EZ was not chosen, or when the company intends to take a margin deduction. The franchise tax home is where the Comptroller prints the row for the report year you are in. We line that row up with the year. The rows stay unmixed.
Form 05-102 is the short report for five kinds of organization when Texas is where they were formed or a place where they have nexus. The walk stops at the first match. A corporation. A limited liability company. A limited partnership. A professional association. A financial institution. A person with authority signs it. Any other taxable entity formed in Texas or holding nexus there uses Form 05-167. Ownership names on that report stay confidential, and the copy the public can open leaves those names off.
Each member of a combined group that was organized in Texas, or that has nexus, still sends a short report of its own. A long form shared by the group does not allow one member to cover the rest. Even in a year whose tax bill is zero, the short report and the franchise report share a single due date. Entities that can skip both reports include exempt entities, entities with no Texas organization and no Texas nexus, passive entities, and a qualifying new veteran-owned business through its first five years while the qualification still holds.
An entity that section 171.0003 calls passive can still have an EZ bill or a long form bill. What that entity skips is the information report, and the two duties stay in that sequence. An officer who changes after the report is filed generally waits for the next annual report. An amended report is the other path, used when something on the filed report was wrong or when the change cannot wait. An agent update is a separate filing at the Secretary of State. A franchise form aimed at May is the wrong paper for that agent update.
If the short report is skipped, the sections that answer are Tax Code sections 171.251, 171.2515, 171.252, and 171.255. One consequence those sections describe is loss of the right to sue or to defend in a Texas court. Officers, directors, partners, members, and owners can also be made personally answerable for certain debts of the company under those same sections. Read sections 171.259 and 171.260 before anyone stretches that personal answerability onto a bank or a financial institution, because those sections stop the stretch. We will not pull those sections past the words printed on them. Bring any forfeiture notice you received and we will open the section number printed on it.
Ending the company, converting it, or merging it calls for a certificate of account status. That ending waits until the final franchise report has been filed and the tax on it has been paid. A company formed in another state gets 60 days for the final report once its Texas nexus has ended. When the payment rules are met, an extension of that final report runs 45 days past the original final due date. Before we build a sequence your letter does not show, we open the Comptroller close instructions beside you.
The annual franchise report for this company aims at May 15. A Saturday, a Sunday, or a day those offices treat as closed pushes that May report to the next day the office actually opens. The move comes from the holiday calendar that is live that year, rather than from a list someone memorized. A late report carries a flat charge of 50 dollars. A tax line that shows zero does not erase that charge.
On the franchise bill, a tax payment that arrives during the first 30 days after it was due adds 5 percent. From day 31 onward that franchise penalty steps up to 10 percent. Interest on the franchise bill starts on day 61. Whatever percent the Comptroller interest page shows for the year of the bill is the percent we use, and this page leaves that percent where the Comptroller printed it.
The original due date has to bring either a Comptroller extension form or a payment that is already on time before a tentative extension exists. The payment is generally either 100 percent of the tax from the prior year or 90 percent of the tax this report will show. On a first annual report, the 100 percent figure taken from the prior year is unavailable if the company only became subject to the tax in that prior year. Filers who are outside the electronic funds rule send the extension through Webfile or on Form 05-164, and November 15 is their extended date.
When franchise tax paid during the prior state fiscal year reached 10,000 dollars, later payment goes by electronic funds transfer. That payer's first extra window aims at August 15, and a further window aims at November 15. A weekend or a holiday shifts either date, and we look the shift up rather than guessing. At 500,000 dollars or above, the extra time is requested inside TEXNET under payment code 13080, and Form 05-164 stays unused. TEXNET states the hour a payment must land, and we copy that hour off the extensions page on the day of the request.
Texas sales tax sits next to the income return, while the franchise report and Form 1120-S each remain a filing of their own. The state portion is 6.25 percent on retail sales, on leases, and on rentals of most goods, and on taxable services. Local tax charged by the city, the county, or a transit district is capped at an extra 2 percent. Add the state rate to the local rate and a buyer still stops at 8.25 percent on one sale. The place of the sale sets the rate. On the day of the sale we open the locator on the Comptroller site, because a city's rate is not a number this page memorizes.
Once a permit is approved, the Comptroller's letter tells the seller whether the rhythm is monthly or quarterly. A monthly report is due on the 20th of the month that follows the reporting month. The sales page uses April as its worked example, and that April example is due on May 20. Quarterly reports land in April, July, October, and January. A seller placed on a yearly rhythm sends the prior year's sales figures on the 20th day of January. When the due date is a Saturday, a Sunday, or a legal holiday, it shifts to the next working day, and we check that calendar in the year of the filing.
A seller who holds a permit may take a discount of 0.5 percent of the tax that was reported and paid on time. Prepaying the sales tax stacks an additional 1.25 percent onto the 0.5 percent discount for paying on time. A report that arrives after the due date draws a penalty of 50 dollars. Sales tax that arrives during the first 30 days after the due date draws 5 percent. Sales tax that arrives more than 30 days after the due date draws 10 percent. Interest begins 61 days after the due date, and the percent remains on the interest page.
When a marketplace already collected the tax, the books have to show that collection so the same sale is not taxed a second time. Form 01-339, the resale and exemption certificate, is what the seller keeps when the buyer truly intends to sell the item again. A permit number standing by itself is not that certificate. A remote seller should read the Comptroller remote-seller page before assuming a permit is required. The safe harbor discussed on that page is 500,000 dollars of Texas sales, and the figure should be confirmed there in the year of the question, because a threshold can move. The sales tax page stays beside the franchise page on our call. Those two pages run two calendars.
The folder for the video call should hold the certificate or the state receipt, the federal form or the acceptance, and the agent name as the state site prints it. If a Comptroller letter is the paper sitting on the counter, that letter comes too. A closed month is enough to start, and so is the plain news that no month has closed yet. Bank logins wait for a written scope. The first note does not ask for them.
Name the act the receipt bought, whether that act was formation, a change of agent, or an amendment. Also say whether Form 2553 was never started, was signed and still waiting on acceptance, or was already accepted. Those two answers keep a Wednesday gap from opening in the conversation. They also tell us whether May is a franchise report, an information report only, or a letter about a report someone skipped.
Steven Palmieri, Tax CFO and the Entrepreneur's CFO, keeps this practice in Dallas with the people who close the month. The state office keeps the public record. The Comptroller keeps the franchise calendar and the sales calendar. A provider you already run keeps payday after the acceptance. A lawyer keeps the company agreement and the question of who is liable. We can gather the facts a form is asking for, and we can keep both calendars. The lawyer's work stays with the lawyer.
The national pages on this address stay with the federal form, the receipt, and the books. This page is the Texas chapter. A company that is outside Texas belongs on those other pages. A Texas company should bring the papers, and we will read the receipt before we read anything else.
Certificate, acceptance, or a Comptroller letter. One line is enough.

You will be talking to the Steven Palmieri practice.